Home / Shipping to Jersey / Shipping from China to Jersey: St Helier, 5% GST & What the £135 Line Really Does
How to Ship from China to Jersey: St Helier, 5% GST & What the £135 Line Really Does
Jersey runs its own tax and customs system, and the part that catches first-time importers is not the rate. It is a single figure that does two different jobs at once, and the second of those jobs is the one nobody warns you about.
Below that figure, no customs duty is charged and no import declaration is required. Above it, a customs declaration is required even in the case where the goods and services tax has already been collected from the buyer at the point of sale. Paying the tax does not remove the paperwork, and that is the mistake this page exists to prevent.
This guide covers where the line sits and what it governs, how the five per cent is calculated, what happens on the two sides of the line, routing into St Helier Harbour and Jersey Airport, the excise and impot charges that sit outside the goods and services tax, and the documents that keep a consignment moving.
At a glance
Status: Crown Dependency with its own tax and customs system · Consumption tax: goods and services tax at five per cent · De minimis line: one hundred and thirty-five pounds, below which no customs duty is charged and no import declaration is required · Above the line: a customs declaration is required even where the tax has been collected at the point of sale · Tax base: sale price plus customs duty plus insurance and freight · Customs: in a customs union with the United Kingdom, Guernsey and the Isle of Man · Main port: St Helier Harbour · Airport: Jersey, JER · Currency: pound sterling
How your cargo moves: China to Jersey
Eight steps from your supplier's door to yours. The last four are the ones shaped by local rules.
- Pickup from your supplierWe collect the goods anywhere in China and bring them to our consolidation point.
- Export clearanceChina customs declaration filed and released before the goods move to the port.
- Loading and departureContainer loaded, sealed and handed to the carrier at the Chinese port.
- Main carriageOcean or air movement booked on the route agreed for your cargo.
- Land at a United Kingdom portMost sea freight discharges at a port such as Southampton or Portsmouth, and the crossing to the island is booked with the ocean leg.
- Cross to St HelierThe consignment arrives at St Helier Harbour, or at Jersey Airport for air cargo, and the question of which side of the line it falls on is settled at this point.
- Tax and duty on the customs valueGoods and services tax at five per cent on a base that includes duty, insurance and freight, with duty assessed above the de minimis line.
- Release and island deliveryOnce the assessment is settled the goods move to the consignee, over a road network that sets its own limits on vehicle size.
Duty rates, VAT rates and clearance times move, and the figure that applies to your goods is the one set for your commodity code on the day of clearance. We check the current position against your code before your goods sail and confirm it to you in writing — ask for that check when you request a quote.
One number, two jobs: what the line does and does not do
The de minimis level for goods and services tax on unaccompanied imported goods was reduced from two hundred and forty pounds to one hundred and thirty-five pounds, and that figure now does two separate things.
The first job is the one everybody expects. Below one hundred and thirty-five pounds, no customs duty is charged on the importation, and no customs declaration is required to support it.
The second job is the one that costs money. Above one hundred and thirty-five pounds, a customs declaration is required because duty may be applicable, and that requirement stands even where the goods and services tax has already been paid to the retailer who sold the goods. A buyer who has settled the tax at the checkout and concluded that the paperwork is finished will find otherwise.
Put plainly: the tax and the declaration are two different obligations. Settling one does not discharge the other.
How the five per cent is calculated
For imports from outside the United Kingdom, the value on which goods and services tax is calculated is the sale price of the goods plus customs duty plus insurance and freight. The carriage cost is inside the base, not outside it.
That matters more than it sounds, because on a long ocean leg from China the freight is a meaningful part of the figure. Calculating the tax on the invoice alone understates it, and understating it by a consistent margin is how a buyer ends up with a pricing model that loses money on every order.
Paying at the checkout does not end your obligations
Where an overseas seller is registered for goods and services tax in Jersey, the tax can be charged at the point of sale and accounted for by the seller. Where the seller is not registered, the supply is still zero-rated in the country of dispatch, and the tax is payable by the customer on importation instead.
Neither route removes the declaration requirement above the line. The two are administered separately, and assuming they are the same process is the commonest first-shipment error on this lane.
What the customs union with the United Kingdom and Guernsey achieves
Jersey is in a customs union with the United Kingdom, Guernsey and the Isle of Man, which allows tariff-free movement between the four territories and applies a common customs tariff to trade with everywhere else.
For a buyer importing from China, that union does not reduce anything. Chinese-origin goods arrive from outside the union and are treated accordingly. What the union does affect is the onward movement of goods that have already cleared inside it, which is worth knowing if your goods are being routed through the United Kingdom first.
St Helier Harbour, and the crossing that comes first
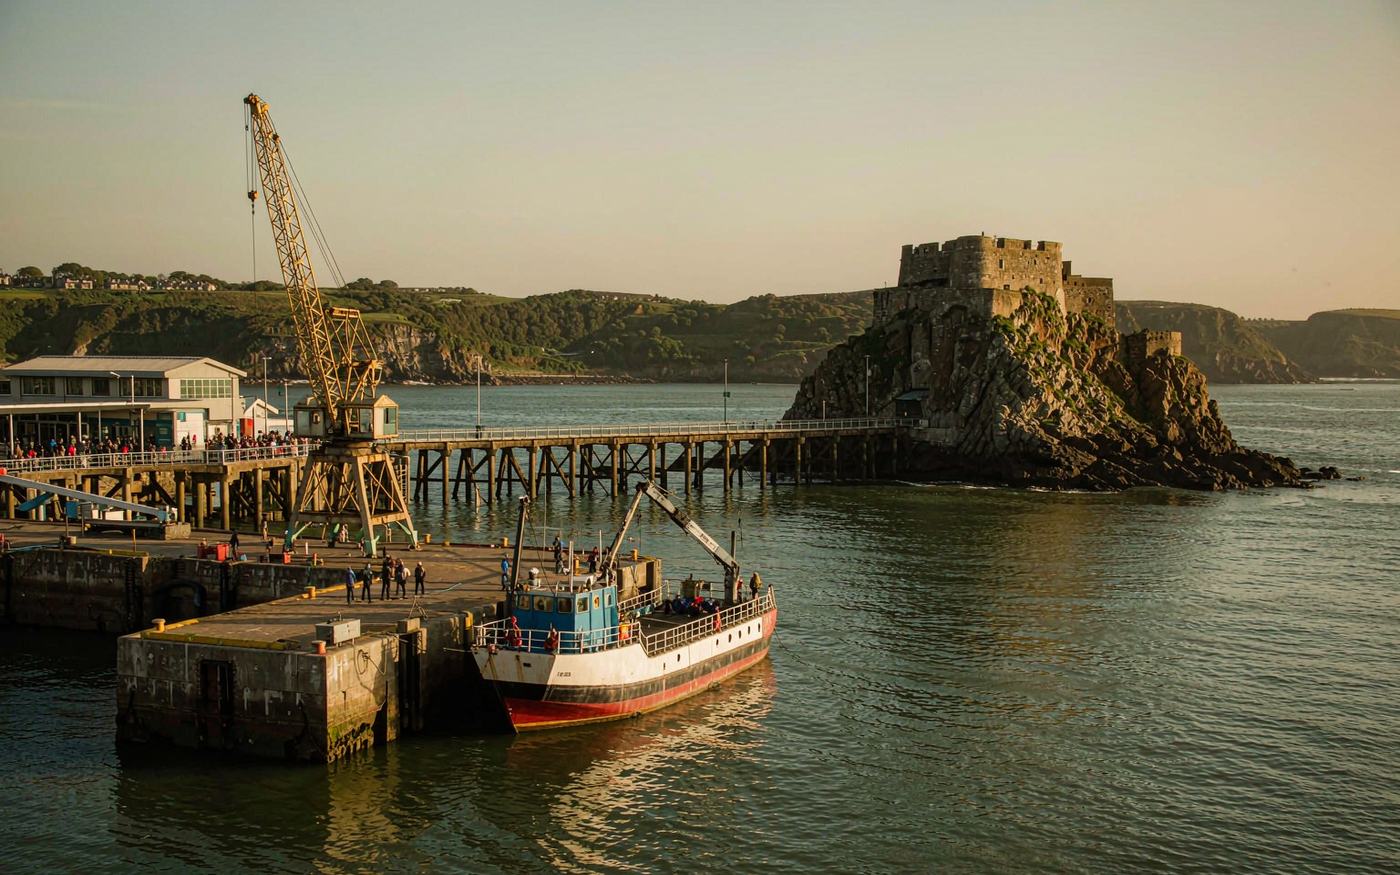
St Helier Harbour is the commercial gateway. Full container loads and consolidated cargo land there, and the deconsolidation point for groupage is at the port.
As with the other Channel Islands, very little arrives direct. Services discharge at a United Kingdom port and the container crosses on a feeder or ferry, and that crossing has its own schedule which needs to be booked with the ocean carriage rather than after it.
Air cargo into JER, and the hub it comes through
Jersey Airport handles air cargo, with most shipments connecting through a United Kingdom hub. The connection, not the flight, is what sets the transit.
Air suits samples, urgent spare parts, high-value retail lines and short-run seasonal stock. It ends at the airport cargo terminal and the consignee arranges the entry and collection.
Excise and impots: the charges that sit outside the goods and services tax
Alcohol, tobacco, road fuel and vehicles carry their own duties here, charged separately from the goods and services tax and calculated on their own basis. They are not covered by the de minimis line in the way buyers expect.
If your consignment touches any of these categories, establish the treatment before you quote. They are the charges most often left out of a first landed cost calculation, and the ones least likely to be waived.
Documents that get a Jersey parcel held
A consignment is held when the description of the goods is too vague to assess, when the value is missing, or when the carriage cost is not declared. These three fields decide whether a parcel clears, and they are filled in by the sender rather than resolved by the authority.
A description such as gifts or household items is not sufficient. What is needed is what the item actually is, in enough detail that duty can be assessed on it without further enquiry.
Packing and delivery on an island with narrow roads
Cargo to Jersey is handled more times than cargo to a mainland port, and the final delivery runs on a road network that restricts vehicle size. Palletised freight has weight limits per pallet for tail-lift delivery.
Packing for a single mainland delivery is packing for fewer handlings than will occur. Specifying for the real number of handlings is the cheapest insurance on the lane.
Choosing an incoterm when the buyer clears on the island
Our services to Jersey are port-to-port, airport-to-airport or depot-to-depot, and the consignee handles the entry and the onward movement. That makes the incoterm a substantive choice, because it decides who is the importer of record for an entry that has to be filed locally.
For a first shipment, put that responsibility with whoever can actually discharge it, and agree it before the goods ship rather than when the container is already on the quay.
Confirming the figure before you quote
The de minimis level has been reviewed more than once and the position can move. The figure that governs your consignment is the one in force on the day of clearance, applied to your commodity code and to the customs value we have calculated.
We confirm the current position against your code while the goods are still in China and give it to you in writing. Ask for that check with your quote.
Real examples on the China to Jersey lane
Five shipments bought in China and delivered into Jersey, told end to end — where the order came from, how it moved, where it nearly went wrong, and how it finished. Client names are withheld at their request; the situations and the handling are what we deal with on this lane.
The line · first parcel · Shenzhen to St Helier
The purchase. A buyer new to importing assumed that paying the tax at the checkout finished the process for a consignment above the line.
The move. Consolidated cargo with the customs declaration prepared and filed even though the tax had been collected at the point of sale.
Where it nearly went wrong. Above the line a declaration is required because duty may apply, and that obligation is separate from the tax. Settling the tax at the checkout does not discharge the declaration, and the consignment waits until the declaration exists.
How it finished. We prepare both now. Nothing of his has been held since.
Freight inside the base · costing · Ningbo to Jersey
The purchase. A first-time buyer calculated the five per cent on the invoice value alone.
The move. Full container with the tax assessed on sale price plus duty plus insurance and freight, as the rule requires.
Where it nearly went wrong. The carriage cost sits inside the base rather than outside it, and on a long sailing from China it is not a rounding difference. Calculating on the invoice alone understates the tax on every single order.
How it finished. He models the full base now. His landed costs have matched the assessment every time.
A vague description · held at the port · Guangzhou to St Helier
The purchase. A buyer declared a mixed consignment as gifts and household items and could not understand why it stopped.
The move. Consolidated cargo declared item by item, with the value and the carriage cost stated separately on the paperwork.
Where it nearly went wrong. The description, the value and the carriage figure are the three fields that decide whether a consignment clears. They are supplied by the sender, and a vague description is not something the authority resolves for you.
How it finished. We write the declaration up front now. Nothing of his has been held for description since.
Excise · outside the tax · Yiwu to Jersey
The purchase. A buyer shipping drinks assumed the goods and services tax was the only charge to consider.
The move. Consolidated cargo with the excise and impot position established before the order was confirmed.
Where it nearly went wrong. Alcohol, tobacco, road fuel and vehicles carry duties that are separate from the goods and services tax and calculated on their own basis. They do not behave the way the de minimis line does, and they are rarely waived.
How it finished. He costs them separately now. No consignment of his has come up short since.
The crossing · a booked leg · Shanghai to Jersey
The purchase. A buyer quoted the ocean transit to his customer and treated the crossing as something that would sort itself out.
The move. Full container with the feeder crossing booked at the same time as the ocean carriage and both counted in the quoted transit.
Where it nearly went wrong. The crossing is a scheduled service with its own timetable rather than a consequence of the ocean leg. Booking it afterwards is booking it around whatever space is left, and on an island lane that costs weeks.
How it finished. He books both together now. His dates have held ever since.
Why importers use Goodhope on this lane
Six things that are different about working with us on China to Jersey shipments.
Get a Jersey quote with the tax and the declaration both mapped out
Tell us what you are shipping and what it is worth. We will confirm which side of the line your consignment falls on, calculate the tax on the correct base, set out the routing including the crossing, and quote every charge separately.
Get a quote Talk to usRelated pages
Frequently asked questions
What is the de minimis line for imports into Jersey?
One hundred and thirty-five pounds. Below it, no customs duty is charged and no import declaration is required. Above it, a declaration is required because duty may apply.
Is a declaration still needed if GST was paid at the checkout?
Yes, above the line. The tax and the declaration are separate obligations, and settling the tax does not remove the requirement to declare.
What rate is goods and services tax charged at?
Five per cent, on the sale price of the goods plus customs duty plus insurance and freight.
Is freight included in the tax base?
Yes. Insurance and freight sit inside the base rather than outside it, which is why calculating on the invoice alone understates the tax.
Which port does sea freight to Jersey use?
St Helier Harbour. Most services discharge at a United Kingdom port such as Southampton or Portsmouth and the container crosses on a feeder or ferry service.
Can air freight be booked to Jersey?
Yes, to Jersey Airport. Most shipments connect through a United Kingdom hub, and that connection sets the transit.
Are excise duties separate from GST?
Yes. Alcohol, tobacco, road fuel and vehicles carry their own duties, calculated on their own basis and outside the goods and services tax.
What causes a parcel to be held by Jersey customs?
A description that is too vague to assess, a missing value, or an undeclared carriage cost. Those three fields decide whether a consignment clears.
Do you deliver door to door in Jersey?
No. Services are port-to-port, airport-to-airport or depot-to-depot. The consignee handles the entry, the charges and the onward collection.
Can the de minimis level change?
It has been reviewed more than once. We confirm the position in force against your commodity code while the goods are still in China and give it to you in writing.