Documents
Customs does not read your invoice for accounting. It reads it to find out whether the shipment matches a known product, a known value and a known buyer. Every mismatch interrupts that reading.
Contents
The commercial invoice is a bill and a declaration at the same time. It states what was sold, to whom, for how much and on what terms. Customs reads it to establish value, classification and admissibility; the bank reads it to release payment; the broker reads it to file the entry.
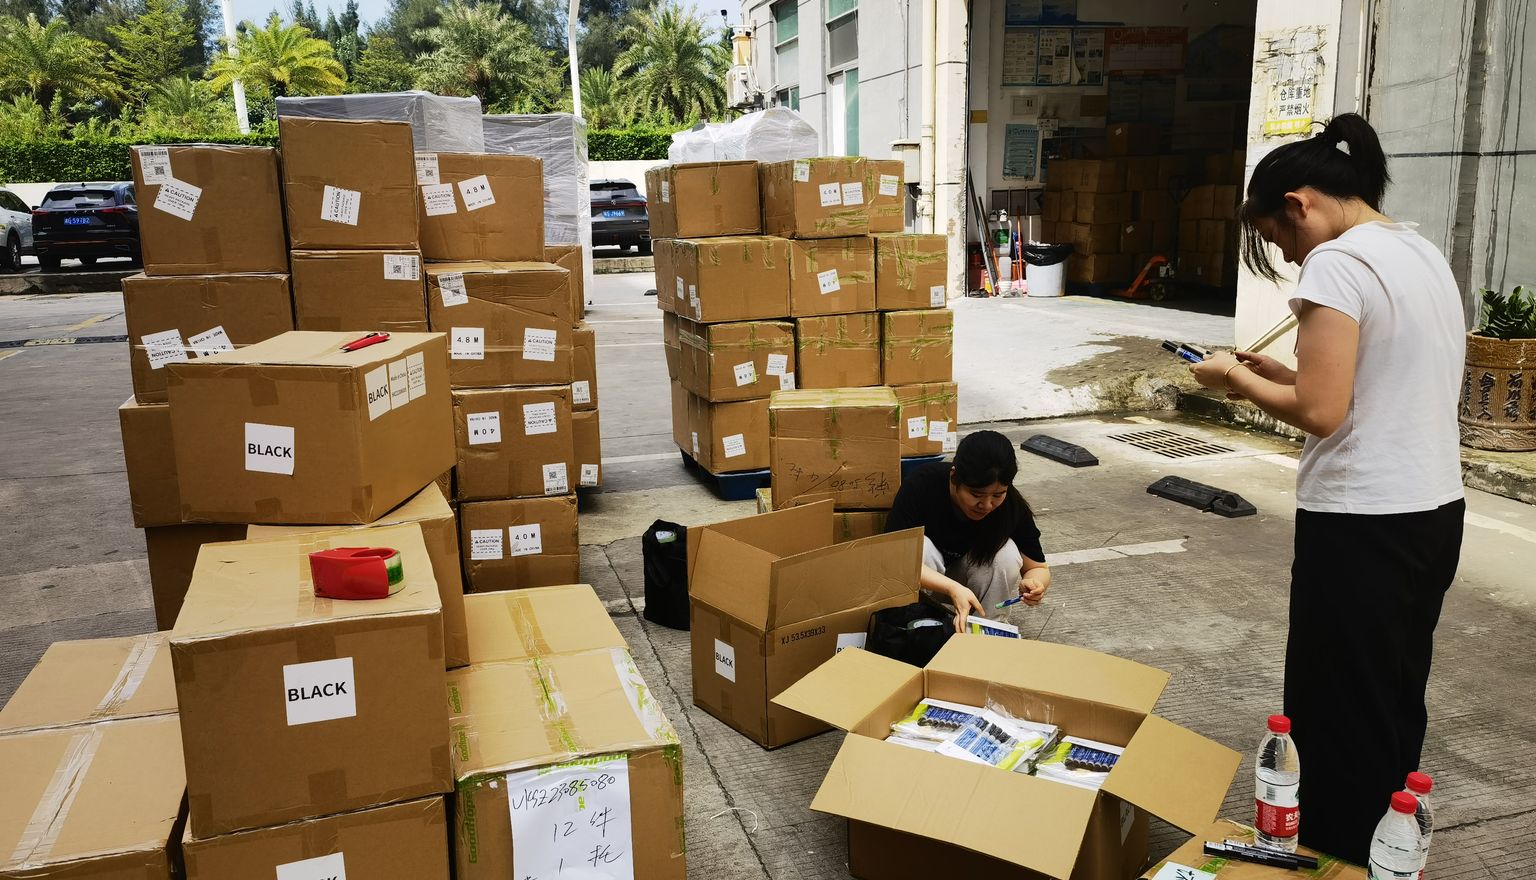
The packing list is a physical description. It states what is in the box, how many boxes, what each weighs and how they are marked. It has no prices, and that is its value: it can be handed to a warehouse or a surveyor without disclosing commercial terms.
They are two views of one shipment and they must agree. When a customs officer finds a quantity that differs between them, the natural next question is which other document is also wrong. That question is expensive, because answering it means examining the cargo.
Most invoice templates have the right boxes and the wrong content. The boxes are not the problem; the entries are.
A description that says samples, parts or machinery invites a question that a specific description answers before it is asked. The most common cause of an examination is a vague line, not a wrong one.
A packing list is a working document. It is used at the factory, at the warehouse, at the gate and at destination, and each of those users needs something slightly different from it.
At minimum it carries package count and type, the contents of each package or group of packages, net and gross weight per line, total volume, and the shipping marks as they appear on the carton. Where a consignment contains mixed cartons, the list has to describe the mix rather than average it.
The most useful packing lists add three things: dimensions per carton type, so volume can be checked rather than believed; a package numbering scheme that a warehouse can follow; and a note of which cartons are loaded at the door and which at the nose, for a container that will be destuffed in sequence.
For LCL cargo the packing list becomes more important, not less. A consolidated container is destuffed by a station that has never seen your goods, and the only description of what belongs to whom is the mark and the list.
The failures repeat, and they are all small enough to look trivial on a screen.
| Mismatch | What customs sees | Result |
|---|---|---|
| Quantity differs by a few units | Goods added or removed after documentation | Examination, amended entry |
| Gross weight on invoice, net on packing list | Inconsistent measurement basis | Query, delay while corrected |
| Description in two registers | Description written for a different product | Reclassification risk |
| Package count differs | Part shipment or missing cartons | Shortage investigation |
| Consignee spelled differently | Different legal entity | Entry rejected at filing |
| Value below the price actually paid | Underdeclaration | Valuation query, penalty exposure |
Typical mismatch types and their usual consequences. How each is handled depends on the destination administration.
Weight is the mismatch that catches careful people. A packing list showing net weight, an invoice showing gross, and a carrier manifest showing a third figure is not a fraud, it is three people using three conventions. It still stops the container, because the declared weight no longer reconciles with the bill of lading.
Volume is the quiet one. Invoice, packing list and booking each carry a figure, and the booking figure is often a rounded estimate given before the cartons were measured. Where the bill of lading shows a volume the packing list contradicts, the difference is usually rounding, and it still reads as a discrepancy. Measure the cartons, put the measured figure on both documents, and let the booking follow.
Declaring a value of zero or one dollar for a commercial shipment is the single most reliable way to invite a valuation query. Customs values goods at what they are worth, not at what the invoice says, and a nominal figure is treated as a statement that needs checking.
Samples are legitimately different from goods. Genuine samples, marked as not for resale, in quantities consistent with sampling and of no commercial value, are often admissible at a low or nil value under a specific procedure. The same cartons, in retail packaging with barcodes and price tags, are goods, whatever the invoice calls them.
Where a supplier includes free items with an order, the honest treatment is to show them at their real value with a zero charge, so the entry reflects what arrived. Hiding them inside a paid line works until the quantities are counted.
Freight and insurance are part of the customs value in many destinations, depending on the term. An FOB invoice into a market that values on CIF will have freight added by the broker. If the freight figure is unknown at the time the invoice is issued, the entry still needs a defensible number.
The invoice names a buyer; the bill of lading names a consignee; the entry names an importer of record. Three roles, often three different parties, and the documents have to make the relationships explicit rather than implied.
Where a buying agent or a Hong Kong trading company sits in the middle, the invoice may come from one entity and the goods from another. That is normal. What is not normal is a certificate of origin issued to a third party with no declaration, or a consignee on the bill of lading that matches nothing on the invoice. Both are fixable in advance and neither is fixable at the destination gate.
Notify party details matter for arrival notices. A wrong email address on the notify party is a missed arrival notice, which becomes demurrage at the terminal, which becomes an argument about who pays it.
Every one of these problems is cheaper to fix in China than at the destination, because at origin the people who know the facts are in the same building as the goods.
Set the template once, with your forwarder, and use it for every shipment. A template with the right fields in the right order removes most errors by removing the decisions. Have the draft invoice and packing list checked against each other before the container is gated in, not after the bill of lading is issued, because after that a correction becomes an amendment with a fee and a delay.
Then keep the final set. Invoice, packing list, bill of lading, certificate and entry, filed together per shipment. A valuation query two years later is answered from that folder or not at all.
Correcting a document after the bill of lading is issued is a different exercise. The carrier amends the bill, the manifest changes, the destination agent is notified, and each step has a fee and a queue. Where the entry has already been filed, the broker amends it, and an amendment on an entry is itself a fact in the record. All of that is avoidable at the point where the draft is still a draft.
Q Can the invoice and packing list be combined into one document?
Sometimes, for simple consignments, but it is a false economy. The packing list is shared with warehouses and carriers who should not see your prices, and customs officers read the two documents for different purposes. Keep them separate and make sure they reconcile.
Q What value should I declare for samples?
A defensible one. Genuine samples in sampling quantities, marked not for resale, can often be cleared at a low value under a specific procedure, but the same goods in retail packaging are merchandise. Declaring a nominal value on commercial goods invites a valuation query and the examination that follows it.
Q Do I need the tariff code on the invoice?
It is not required in every jurisdiction, but including it reduces questions and forces the classification to be settled before shipment. Where a certificate of origin states a code, having the invoice state the same code prevents a preference claim from failing on a technical mismatch.
Q What is the most common cause of a customs delay?
A description too vague to classify, followed by a weight or quantity that does not reconcile between the invoice, the packing list and the bill of lading. Both are documentation problems, both are visible before the container leaves, and both cost storage and demurrage when they are found at arrival.
Q Should the invoice show gross or net weight?
Show both, and say which is which. The most common reconciliation failure is one document using gross weight and another using net, with nobody noticing until a manifest is compared to an entry. A column for each removes the ambiguity.
Q Can I amend the invoice after the goods ship?
You can, but each amendment ripples: the bill of lading, the certificate, the entry and sometimes the letter of credit all reference the original. An amendment after departure is a fee and a delay at best, and a refused preference claim at worst.
Related pages
Send us your draft invoice and packing list before the booking. We will compare them line by line and tell you what a customs officer would query.
Email sales8015@goodhopefreight.com | WhatsApp & phone +86 133 9216 2503